

You are using an unsupported browser that may limit access to certain website applications. If you continue, you may not be able to access certain pages or process requests. Please use one of our recommended browsers to experience the website properly.
Caring for loved ones while working?
How to maximize your employee benefits
October 19, 2026
Do you manage meetings during the day and medication schedules at night? Coordinate kids’ school pickups and parents’ doctor appointments? If you’ve ever answered work emails from doctors’ offices, you might benefit from additional resources and support.
Seven in 10 family caregivers are employed, but many face disruptions and lack access to supportive benefits, especially the 18 million hourly wage workers.1 Those that have benefits may not tap into the ones that may help them most.
Your EAP: Because your mental health matters
Many caregivers (64%) experience high emotional stress and physical strain (45%).1 Employee Assistance Programs (EAPs) provide resources to help empower employees and families to navigate personal, emotional and health-related challenges.
Many employers offer an EAP, which is typically a no-cost to employees, confidential benefit that offers access to such services as:
- Counseling and mental health support — for stress, grief, anxiety or relationship strain
- Legal consultations — help with guardianship, estate planning or navigating elder care paperwork
- Financial guidance — resources to help you manage the expenses of caregiving
- Referrals to local care services — so you don’t have to search for quality care in your free time
- Some EAPs provide access to mental health services for dependents too, which could help alleviate more strain that may be affecting you and your family
Caring for loved ones can provide a sense of purpose, but it can be stressful, as well. If you start to feel that stress, consider your EAP options: There’s typically no out-of-pocket cost to you for the services you access. Contact your employer for additional information on the EAP services available to you.
Paid and Protected Leave: Know your eligibility
In some cases, your caregiving responsibilities may overlap with your work schedule. But your job — and your employer-sponsored benefits — are important to you and your loved ones’ care.
First, you’ll want to explore if flexible work hours or virtual work are available to you. That way, you can provide transportation, attend doctor’s appointments or even work from waiting rooms without sacrificing work hours.
Contact your HR department and ask: “What flexible work, paid or protected leave options are available to me to care for a family member?”
If that’s not possible, you still have options. Under the Family and Medical Leave Act (FMLA), eligible2 employees may take up to 12 weeks of unpaid, job-protected leave per year to care for a seriously ill family member.3 Your position, including your benefits, are protected while you’re away.
Some employers go further and offer paid caregiver leave as part of their benefits package. Additionally, several states have enacted Paid Family Leave (PFL) requirements aimed at easing employees’ financial burden when they need to take time from work to act as a caregiver.
Employers should consult their own employment or benefits counsel for advice concerning their specific obligations under state-mandated paid family and medical leave laws.
Flexible accounts: The opportunity to save money for eligible expenses
If you’re paying out-of-pocket for dependent care (whether an aging parent, a child with special needs or otherwise) you have a couple options that can help make a difference financially.
Option 1: A Dependent Care Flexible Spending Account (DC-FSA)
Your employer may make a DC-FSA available to you. With a DC-FSA, you can set aside pre-tax dollars via payroll deduction to cover eligible caregiving expenses incurred while you are on the plan. That’s a meaningful savings opportunity for costs, or a portion of costs, you already have.
To qualify for use under DC-FSA, expenses must be related to the care of a dependent child (under age 13, or any age with special needs) or dependent adult and must enable you to work or attend school full-time. For a complete list of restrictions and qualified expenses, refer to IRS Publication 503: Child and Dependent Care Expenses.
Additionally, legislative law, in conjunction with the IRS, places limits on how much pre-tax savings you can set aside each year. Visit our IRS limits page for more information.
It’s important to know that the money you place in a DC-FSA is “use it or lose it,” meaning you only must spend the funds by the end of the plan year or they will be forfeited.
Option 2: A Health Savings Account (HSA)
If your health insurance is a high-deductible health plan (HDHP), you may be eligible for a health savings account (HSA).
HSAs allow you to contribute pre-tax dollars via payroll deduction to spend on eligible health expenses for yourself, your spouse and your dependents. Unlike a DC-FSA, funds in an HSA can be used to pay qualified medical expenses today, tomorrow and throughout your retirement years, as long as there is money in the account. It’s not a “use-it-or-lose-it” account and your balance remains with you to use and can also be invested once it reaches a certain threshold. As with any investment, there are risks; make sure to fully explore those risks before choosing to invest your balance.
The IRS sets the annual contribution limits for HSAs, which includes a catch-up amount for ages 55+. It’s worth checking if your employer offers these account options. If they do, consider enrolling the next time you’re eligible.
Log in to your benefits portal to review your coverage and enrollment eligibility options.
You’re not alone: More resources for caregivers
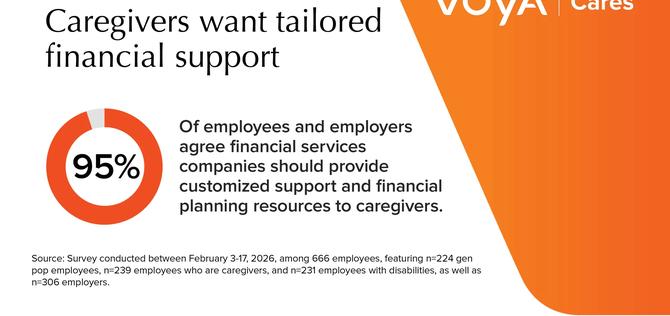
Our research tells us that 52% of employed caregivers say their caregiving responsibilities have impacted their mental health, and nearly half say it’s affected their ability to save for retirement.4
The support you may need — mental, emotional and financial — may already be available. We’re here to help you understand what’s available and feel confident taking the next step.
If your employer offers Voya Cares® benefits, visit Voya Cares resources to explore dedicated resources for those with disabilities and their caregivers.
1 “Caregiving in the U.S. 2025.”AARP and National Alliance for Caregiving. July 2025.
2 “Am I Eligible for FMLA Leave?” Department of Labor. July 2025.
3 “Family Caregivers: Information on the Family and Medical Leave Act” Department of Labor. July 2025.
4 Results of an Ipsos survey in partnership with Voya Consumer Insights and Research conducted Aug. 8–9, 2024, on the Ipsos eNation omnibus online platform among 1,005 adults aged 18+ in the U.S., featuring 164 caregivers (117 White, 39 Asian/Hispanic/Black[Net], 8 other).
This information is provided by Voya for your education only. Neither Voya nor its representatives offer tax or legal advice. Please consult your tax or legal advisor before making a tax-related investment/insurance decision.
Health Account Solutions, including Health Savings Accounts, Flexible Spending Accounts, Commuter Benefits, Health Reimbursement Arrangements, and COBRA Administration offered by Voya Benefits Company, LLC (in New York, doing business as Voya BC, LLC). Custodial services provided by Voya Institutional Trust Company.
This highlights some of the benefits of these accounts. If there is a discrepancy between this material and the plan documents, the plan documents will govern. Subject to any applicable agreements, Voya and its subcontractors reserve the right to amend or modify the services at any time.
The amount saved in taxes will vary depending on the amount set aside in the account, annual earnings, whether or not Social Security taxes are paid, the number of exemptions and deductions claimed, tax bracket and state and local tax regulations. Check with a tax advisor for information on whether your participation will affect tax savings. None of the information provided should be considered tax or legal advice.
Investments are not FDIC Insured, are not guaranteed by Voya Benefits Company, LLC (in New York, doing business as Voya BC, LLC), and may lose value. All investing involves risks of fluctuating prices and the uncertainties of return and yield inherent in investing. All security transactions involve substantial risk of loss.
Not FDIC/NCUA/NCUSIF Insured I Not a Deposit of a Bank/Credit Union I May Lose Value I Not Bank/Credit Union Guaranteed I Not Insured by Any Federal Government Agency
Products and services offered through the Voya® family of companies.
6089197_0526
CN5485150_0728